
Bank Statement Analysis: Complete Guide to Fast, Accurate & Fraud-Proof Results
Table of Contents
[ show ]- Loading table of contents...


Bank statement analysis software converts submitted bank statements into decision-ready financial data. It reads the statements applicants upload, extracts the transactions and balances, and turns them into structured output a lending or risk team can underwrite against.
The dividing line between tools is whether they also verify that the statement itself is authentic before your team relies on it.
Every decision that rests on a bank statement depends on two questions: what does this statement say, and can you trust it? Most software in this category answers the first at scale. The second is where the market splits, and where most buying mistakes happen.
This guide defines the category, maps the three types of bank statement analysis tools you will encounter, and walks through the evaluation criteria and vendor questions that matter before you buy. Inscribe builds software in this category and we note where it fits, but the goal is to help you ask the right questions of any vendor on your shortlist.
What is bank statement analysis software?
Bank statement analysis software ingests PDF bank statements, scanned documents, and photos, and converts them into structured data a lending or risk workflow can act on. Under the hood, AI-powered bank statement analysis typically means optical character recognition (OCR) paired with parsing models that understand statement layouts: transaction tables, running balances, account details, and the formatting quirks of thousands of financial institutions.
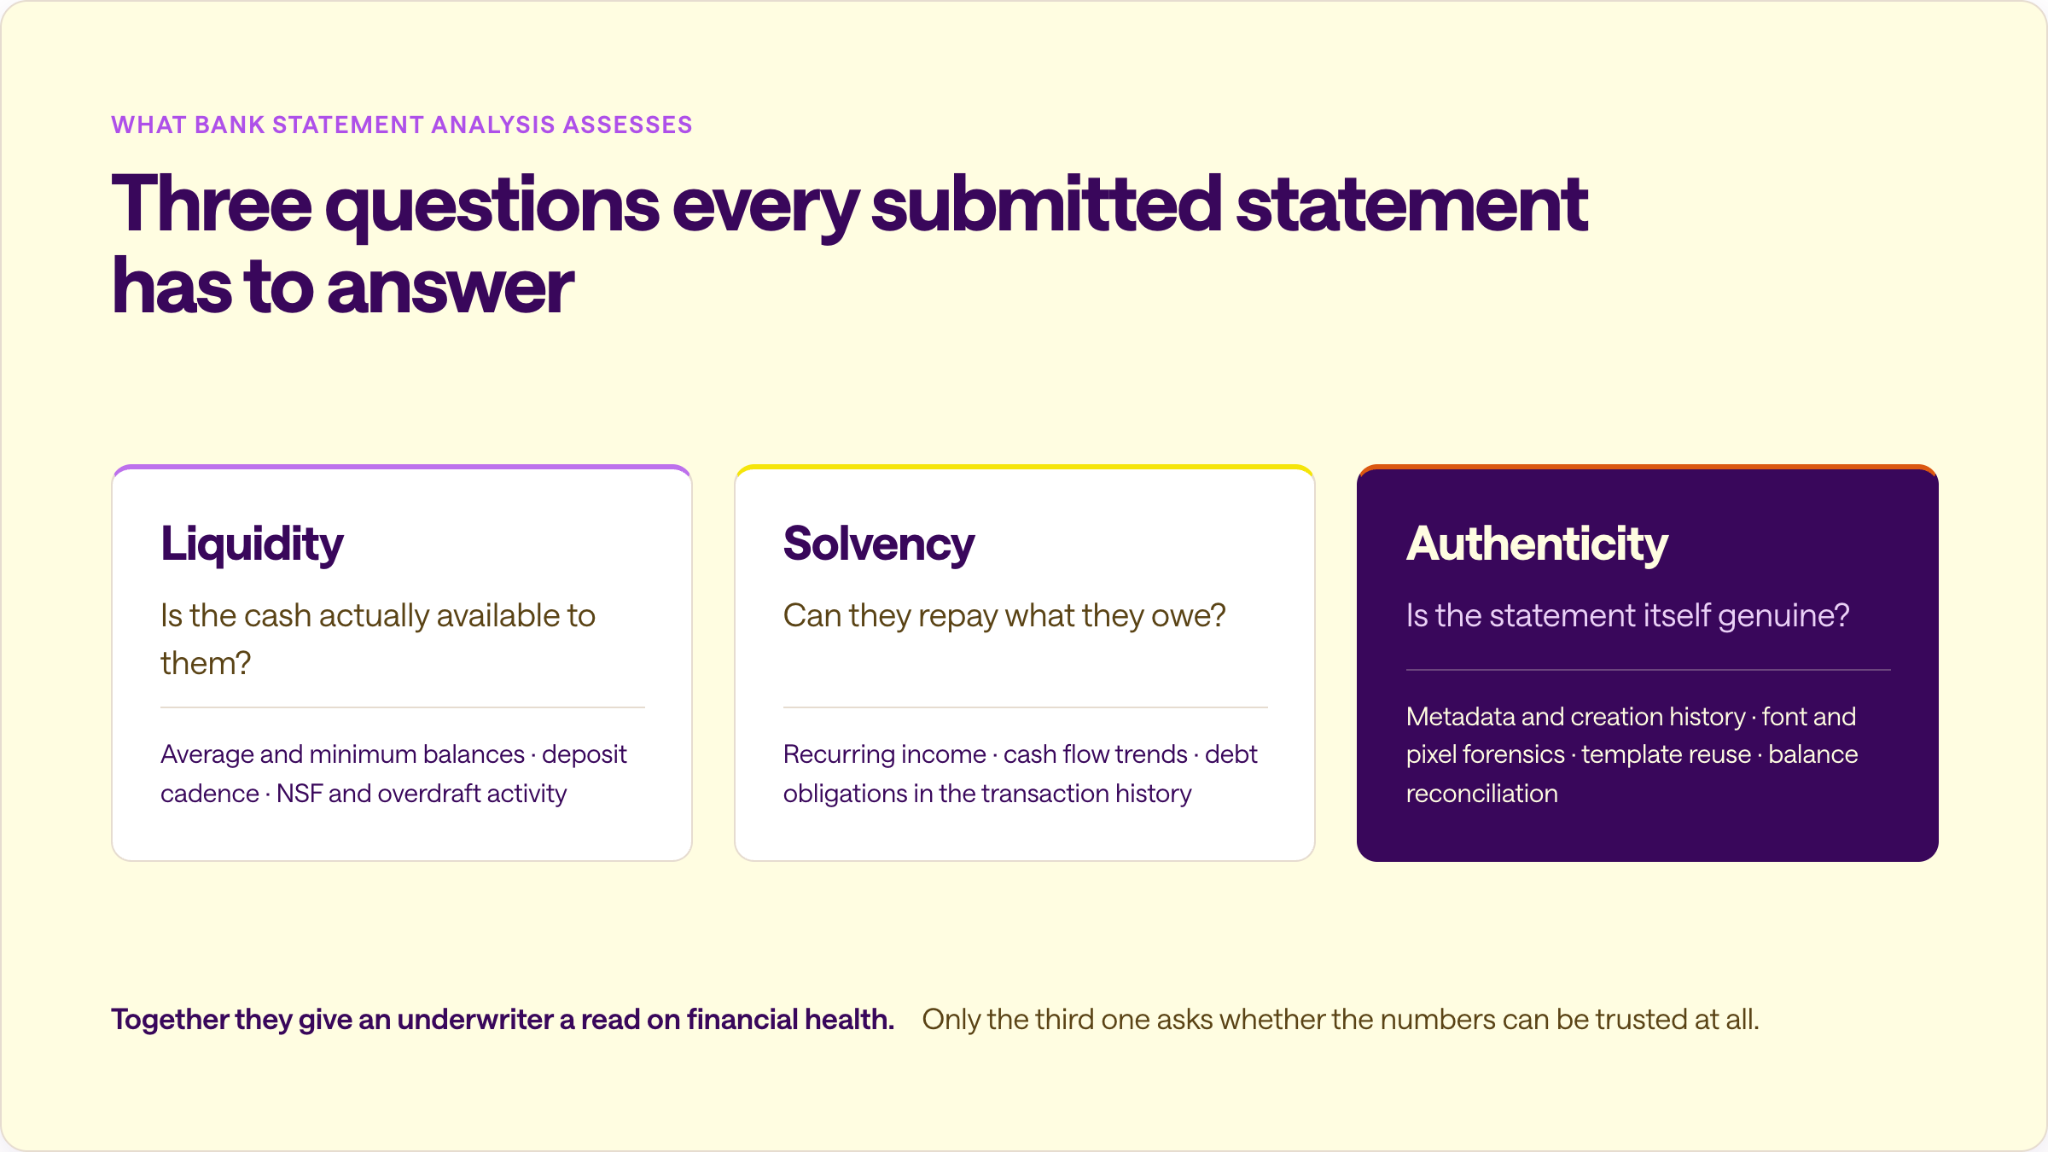
From that structured data, the software runs the financial analysis that drives decisions: recurring income and deposit cadence, average and minimum balances, cash flow trends, overdraft and NSF activity, and debt obligations visible in the transaction history. In credit terms, bank statement analysis assesses three things about an applicant: liquidity, the cash actually available to them; solvency, their ability to repay what they owe; and authenticity, whether the statement and the account it describes are genuine. Together, those give an underwriter a read on financial health. The output feeds an underwriter's review, a loan origination system, or an automated decision engine, most often to verify income and assess repayment capacity.
The alternative is manual review and manual data entry, which takes 10 to 15 minutes per document, introduces human error, varies by reviewer, and does not scale with application volume. For lenders processing high volumes of applications, automated bank statement analysis cuts that per-document time, which is why the category exists. Lenders, banks, credit unions, fintechs, and property managers all use bank statement analysis software anywhere an applicant's financial picture has to be established from documents: consumer lending, business lending, equipment financing, merchant onboarding, and tenant screening.
What are the three types of bank statement analysis software?
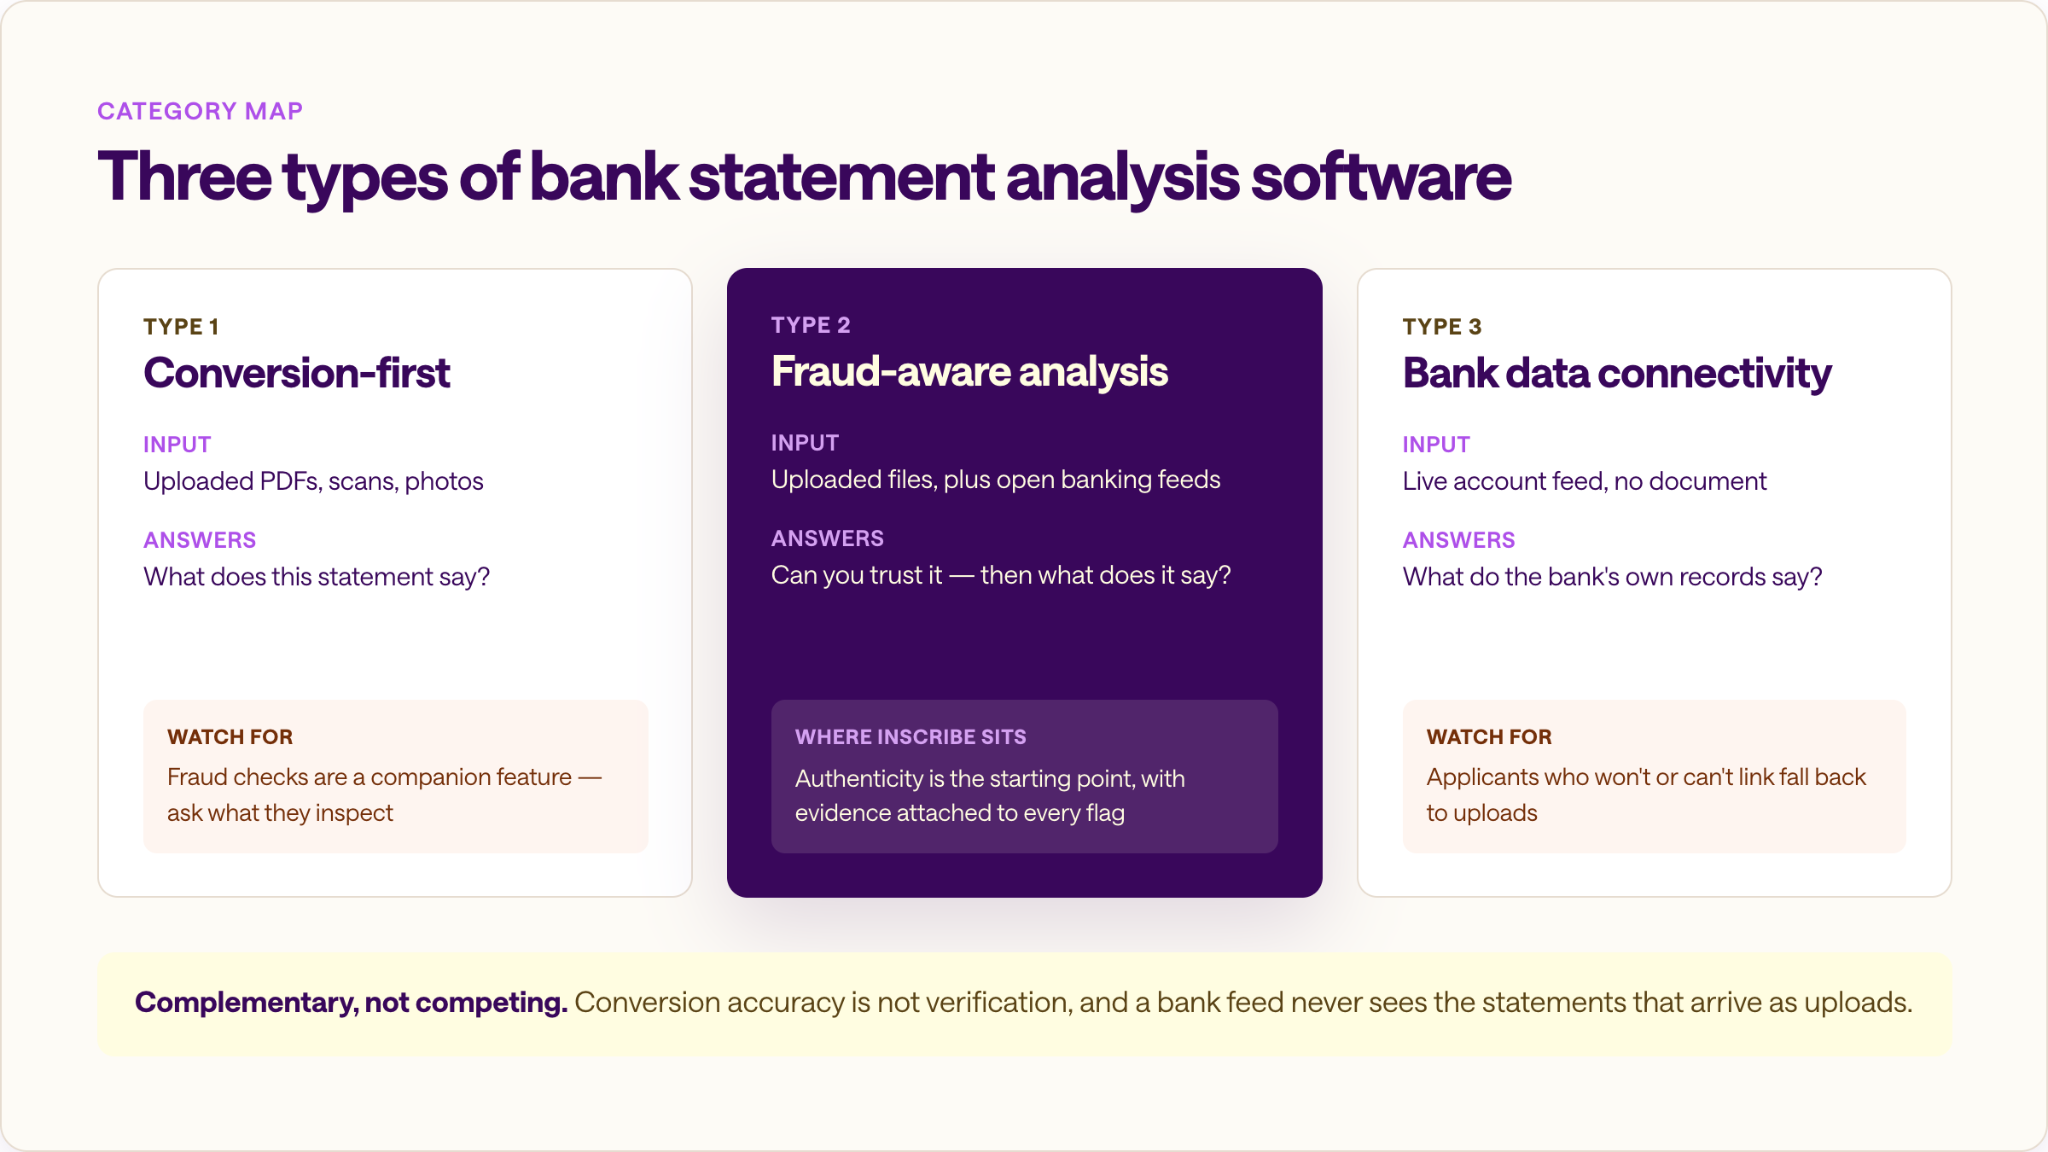
Bank statement analysis software falls into three types: conversion-first tools built around turning statements into data, fraud-aware platforms that verify document authenticity before analyzing it, and bank data connectivity tools that bypass documents entirely by pulling transactions from a live account feed. Most confusion in this buying process comes from a naming problem, since vendors in all three categories describe themselves with similar language. Before you compare features, place each vendor on your shortlist into one of these groups.
1. Conversion-first (extraction-first) bank statement analysis tools
These tools are built around converting statements into data. They use OCR and parsing to read PDFs and images, pull out transactions and balances, and export structured output in spreadsheet and accounting formats. The best of them handle messy inputs well: multi-page statements, scans, photos, and unusual institution formats.
DocuClipper and MoneyThumb both built their businesses on turning statements into spreadsheets and structured exports, and both now offer document fraud checks alongside conversion. MoneyThumb's Thumbprint compares statements against profiles built for thousands of banks. DocuClipper markets metadata, font, and balance reconciliation checks with a composite risk score. Larger document automation platforms such as Ocrolus extend extraction with cash flow analytics for lending and add fraud signals as a component, straddling this category and the next.
The question worth asking a conversion-first vendor is what that fraud layer inspects and what comes back with a flag. Ask how large the document network behind the template matching is, whether the vendor detects fully AI-generated statements rather than only edits to real ones, and whether a flag arrives with evidence a reviewer can act on or with a score alone. Where authenticity is the platform's starting point rather than a companion feature, those answers tend to be specific.
2. Fraud-aware analysis platforms
Fraud-aware platforms do the same extraction and cash flow analysis, and add a layer that verifies document authenticity before the numbers are trusted. That layer inspects the document itself: file metadata and creation history, font and pixel-level anomalies, reused templates seen across a document network, and suspicious transaction patterns, such as transactions that do not reconcile with stated balances. Documents that fail these checks are flagged with evidence and routed to a reviewer instead of flowing silently into a credit model. Inscribe and Resistant AI are examples: platforms specifically trained on financial documents to detect fraud, treating authenticity as the starting point of analysis rather than an add-on.
This is the category where bank statement verification software and a dedicated fake bank statement detector live. If your intake includes uploaded files, this authenticity step is the difference between analyzing what an applicant's finances are and analyzing what a fraudster wants you to believe they are.
3. Bank data connectivity (open banking)
Connectivity tools skip the document entirely. The applicant logs in to their bank account, and the tool retrieves transaction data directly from the institution through a live feed. Plaid and Mastercard Open Banking (formerly Finicity) are the best-known examples. Data quality is high, and there is no document to forge.
The gaps are coverage and completeness. Not every applicant will link an account: some decline, some cannot connect their institution, and some abandon the flow. Those applicants fall back to uploading statements, which the feed never sees. Plaid's own product design reflects this: When an applicant cannot or will not connect a bank or payroll account, submitted documents remain the income data source, which is why Plaid routes uploaded documents through Inscribe for authenticity checks as part of its income verification product.
The two categories sit next to each other in the same workflow: Plaid supplies the connectivity, Inscribe supplies the document analysis. Inscribe also ingests open banking data from providers such as Plaid, so a transaction feed and an uploaded statement can be assessed side by side. Any workflow that accepts uploads still carries document fraud exposure, no matter how good the connectivity path is.
These categories are complementary rather than competing. A common architecture pairs connectivity for applicants who link accounts with a fraud-aware analysis path for the statements that arrive as files. The buying mistake is assuming one category covers the others. Conversion accuracy is not verification, and a bank feed never sees the statements that arrive as uploads.
Why does authenticity belong in the buying decision?
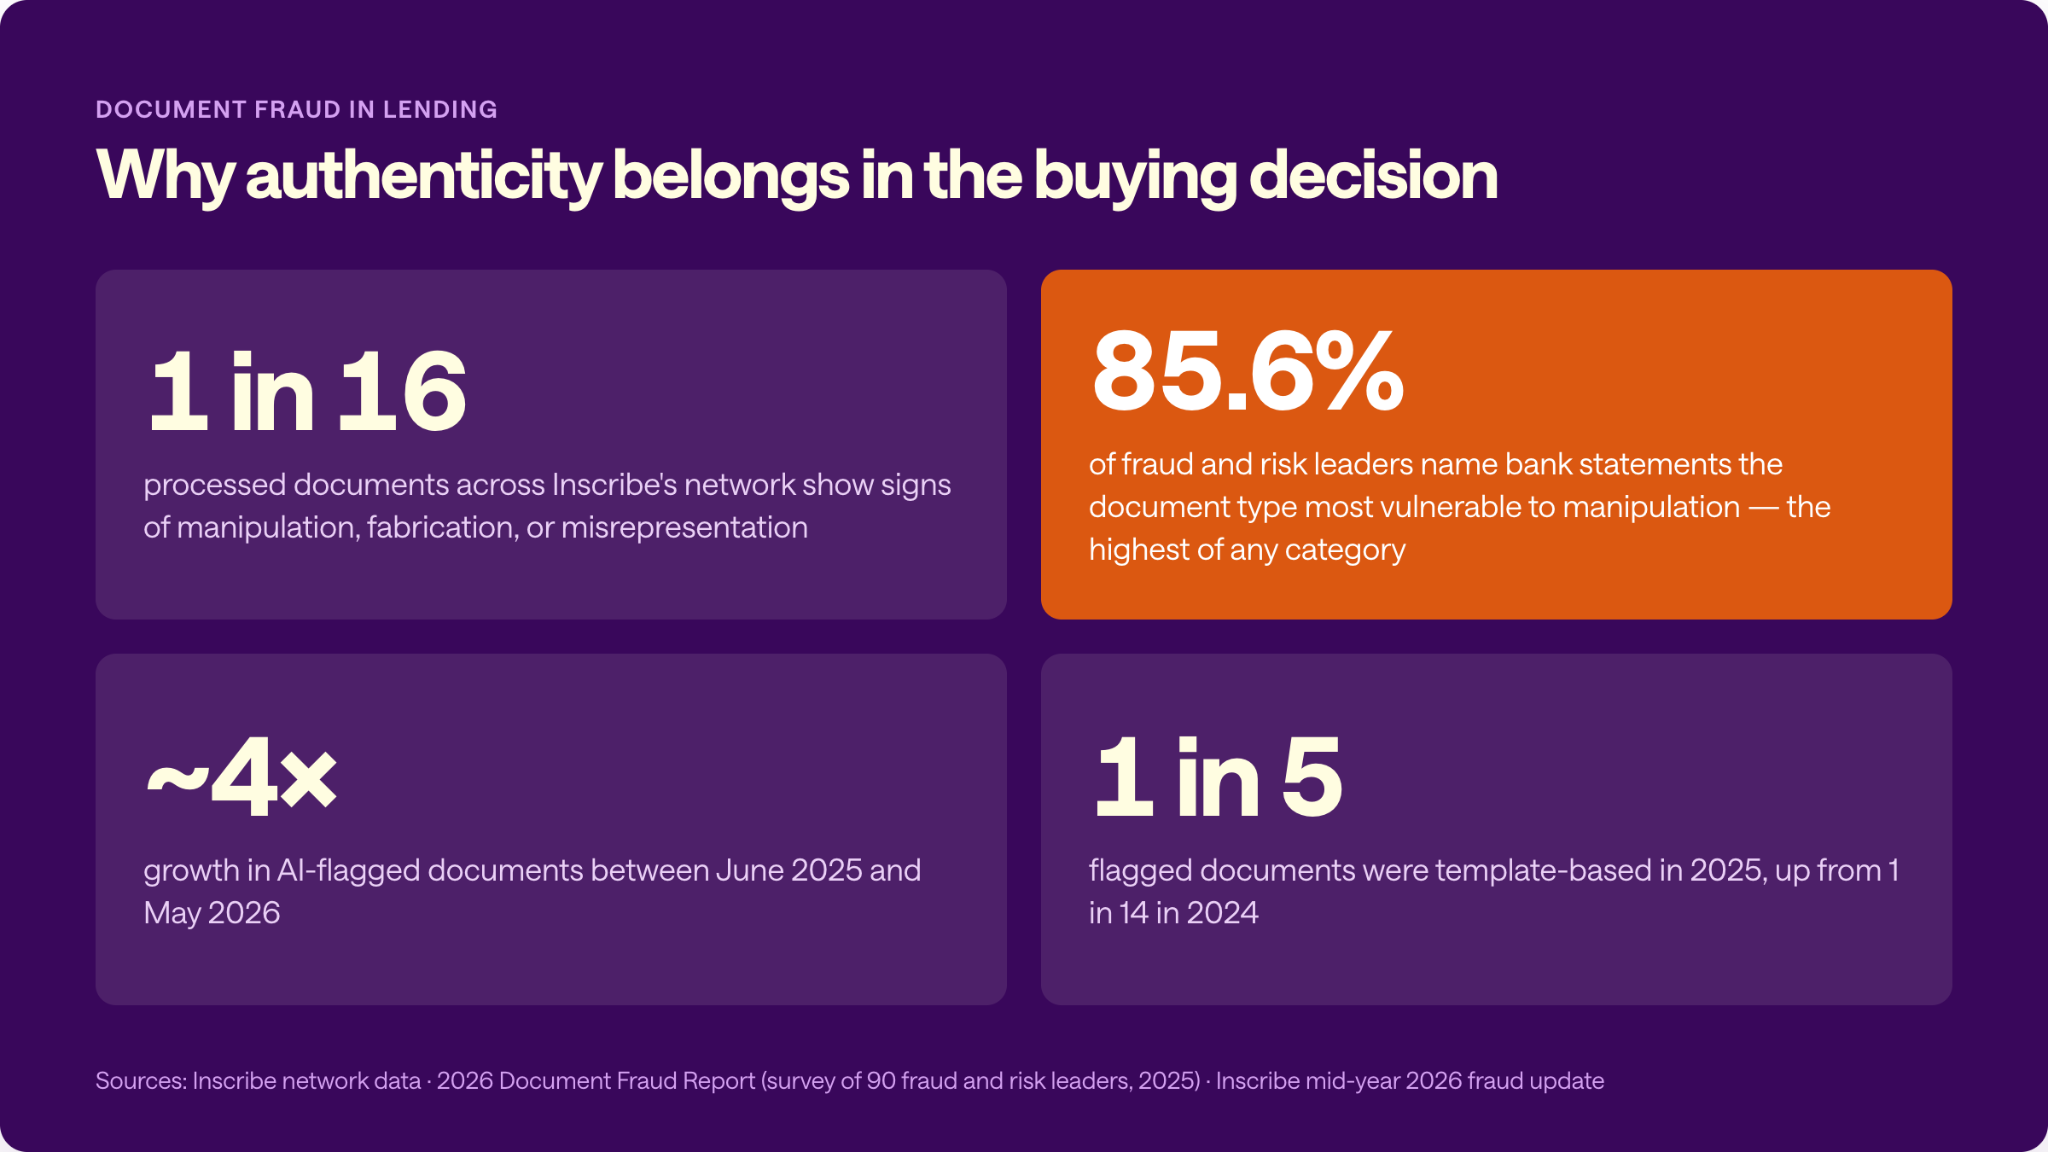
Authenticity belongs in the buying decision because document fraud is now the most commonly reported fraud type in lending, and extraction accuracy offers no defense against it. A few years ago, treating fraud detection as a separate purchase was defensible. The data says it no longer is. In research Plaid conducted with more than 400 lending leaders, 61% said they have experienced document fraud, making it the most common fraud type reported. Across Inscribe's network, roughly 1 in 16 processed documents shows signs of manipulation, fabrication, or misrepresentation. In a 2025 survey of 90 fraud and risk leaders for the 2026 Document Fraud Report, 85.6% cited bank statements as the document type most vulnerable to manipulation, the highest of any category.
The reason is accessibility. Across Inscribe's network, the volume of AI-flagged documents grew roughly 4x between June 2025 and May 2026, per the company's mid-year 2026 fraud update. Template-based fraud remains dominant by volume: in 2025, 1 in 5 flagged documents was template-based, up from 1 in 14 in 2024. Template marketplaces sell editable statements for under ten dollars, and generative tools produce convincing multi-page documents in seconds, with no design skill required. If you want to understand what your fraud teams are up against, see how fake bank statements are actually made and why the standard request for 3 months of bank statements no longer works as a fraud deterrent on its own.
Bank statements are targeted because they are complex, and because they are among the most heavily weighted underwriting documents lenders collect. Dozens of transactions, running balances, dates, and formatting elements create more places to hide a subtle edit than pay stubs or tax forms with a handful of fields, and far more work for a human reviewer trying to catch it. A fraudulent statement that slips through is more than a credit loss; it is an entry point for broader financial crime. That complexity is exactly what makes automated data analysis valuable, and exactly why the analysis has to start with a document it can trust.
What features should bank statement analysis software include?
A complete platform covers eight key features: data extraction and parsing, transaction categorization, income and cash flow analysis, authenticity and fraud detection, explainability and audit trail, routing and workflow, integration, and security certification. Whatever category a vendor sits in, evaluate them against the full set.
- Automated data extraction and parsing. Accurate reading of transactions, balances, dates, and account details across PDFs, scans, and photos, including multi-page and multi-account statements from institutions of every size.
- Transaction categorization. AI-powered categorization of deposits, withdrawals, transfers, and recurring items, so income and obligations can be computed consistently from categorized transactions.
- Income and cash flow analysis. Recurring deposit detection for income verification, average and minimum balance calculations, NSF and overdraft counts, and trend analysis that turns raw transactions into cash flow insights.
- Authenticity and fraud detection. Forensic, template, and consistency checks that verify document authenticity before the data is used. This is the step bank statement verification software performs.
- Explainability and audit trail. Plain-language reasons for every flag, plus logged scores and evidence that hold up in internal audit and regulatory compliance reviews.
- Routing and workflow. Configurable thresholds that clear low-risk statements automatically and send exceptions to a human with the evidence attached.
- Integration. API-first design, webhook support, and structured outputs that feed existing systems, from loan origination to decisioning, without manual entry.
- Security and compliance. Independent certifications such as SOC 2 Type II and ISO 27001, plus data privacy, retention, and deletion controls that protect sensitive financial information and match your regulatory requirements.
How should you evaluate bank statement analysis software?
Evaluating bank statement analysis software takes a structured pilot on your own documents rather than a feature checklist. To choose the right tool, work through these eight criteria with every vendor.
- Start with your document mix and intake channels. Inventory how statements actually reach you: applicant uploads, email attachments, scans from branch staff, photos from mobile, and whether business applicants submit financial statements alongside bank activity. A tool that performs well on clean digital PDFs can fall apart on a phone photo of a printed statement. Your intake reality, not the vendor's demo files, defines the requirement.
- Test extraction accuracy on your own statements. Run a pilot with your hardest documents: multi-account statements, small regional institutions, credit union formats, and statements with unusual layouts. Measure field-level accuracy, not just whether the tool produced output.
- Ask how the tool knows a statement is genuine. This is the question that separates the categories. If the honest answer is that it does not, every downstream metric inherits that blind spot. Look for forensic and metadata analysis, template and network detection, and cross-checks between transactions and balances. A dedicated fake bank statement detector capability is a strong signal the vendor takes this seriously.
- Look for evidence, not just scores. A risk score without an explanation creates reviewer guesswork and audit exposure. Flags should come with specific, plain-language reasons a reviewer can act on and an auditor can follow, supporting informed decisions rather than judgment calls made blind.
- Map the workflow end to end. Understand how results move through your credit decision workflows and your loan underwriting process: threshold configuration, exception routing, reviewer queues, and what happens with inconclusive results. Accuracy that is hard to operationalize slows you down anyway.
- Confirm integration effort before you commit. Review the API documentation before the sales call, ask for typical implementation timelines with engineering teams your size, and confirm webhook support for real-time events. Public, current documentation (for Inscribe, at docs.inscribe.ai) is itself a useful signal of engineering maturity.
- Validate security and governance. Statements contain some of the most sensitive financial data your applicants will ever share, and handling it puts you inside the safeguards requirements of the Gramm-Leach-Bliley Act. Confirm SOC 2 Type II and ISO 27001 certification, data retention and deletion controls, and a published security posture you can share with your own compliance team (see trust.inscribe.ai for the shape this should take). If your fraud program also feeds BSA reporting, confirm the evidence trail exports cleanly for a suspicious activity report to FinCEN.
- Understand the pricing model. Vendors price per document, per page, per application, or per seat, and the differences compound at volume. Model your actual monthly document counts, ask how multi-page and multi-account statements are counted, and confirm whether verification and analysis are priced together or separately.
What questions should you ask on a vendor call?
Eight questions surface the gaps a demo will not. Ask each one and press for a live demonstration rather than a described capability.
- What happens when someone submits an edited or fully generated statement? Show me.
- What is your field-level extraction accuracy on scanned and photographed statements, not just digital PDFs?
- How do you handle statements from institutions you have never seen before?
- What evidence accompanies a fraud flag, and can my auditors follow it?
- How do results route into our loan origination system, and what does implementation take?
- What are your processing times at our peak volume?
- Which certifications do you hold, and what are your retention and deletion controls?
- How is pricing counted for multi-page, multi-account, and resubmitted documents?
Where does Inscribe fit?
Inscribe sits in the fraud-aware category. The Bank Statement Analyzer handles extraction and cash flow analysis, and the fake bank statement detector and bank statement verification layer confirm each statement is authentic and unaltered before its data reaches your decision. Every result returns a Trust Score (0 to 100) with a plain-language summary, in about 72 seconds per document on average. Inscribe has been purpose-built for document risk screening since 2017 and is SOC 2 Type II and ISO 27001 certified.
Logix Federal Credit Union credits this approach with helping prevent more than $3M in potential fraud losses, and BHG Financial used it to replace manual fraud detection with a scalable, transparent system.

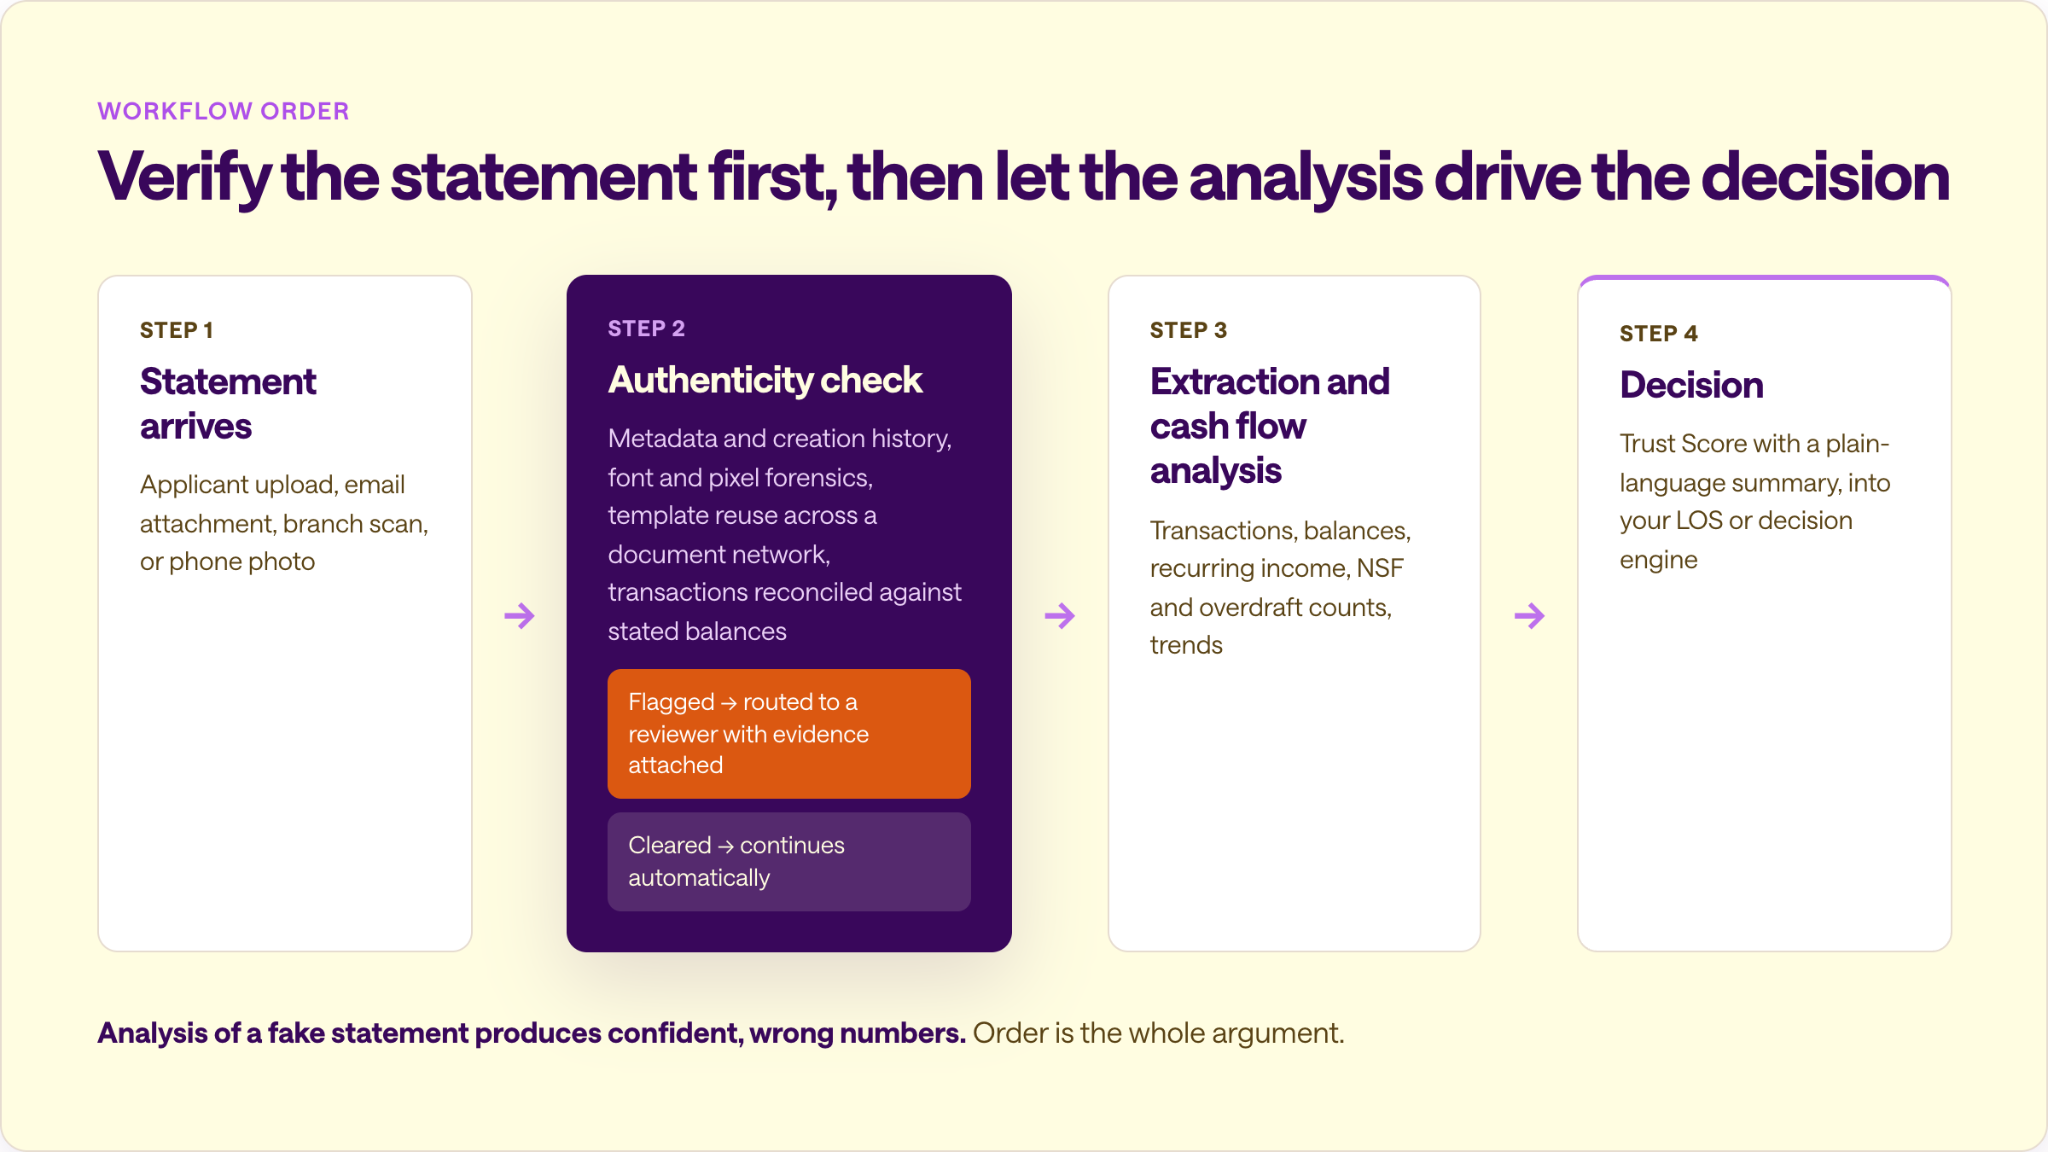
Verify the statement first, then let the analysis drive the decision. See how Inscribe compares as a bank statement analyzer, and go deeper on bank statement fraud detection if uploaded documents are your main exposure.
Frequently asked questions about bank statement analysis software

Bank statement analysis software converts submitted bank statements into structured, decision-ready financial data, extracting transactions and balances and computing income, cash flow, and risk metrics. Sometimes called a bank statement analyzer (or bank statement analyser in British English), these tools differ most in whether they also verify the statement is authentic before its data is trusted, which is the dividing line buyers should evaluate first.
Analysis answers what a statement says: income, balances, cash flow, and obligations. Verification answers whether the statement can be trusted at all, checking for forgery, editing, and fabrication. Verification comes first in a sound workflow, because analysis of a fake statement produces confident, wrong numbers. Bank statement verification software covers that authenticity step in depth.
Open banking (bank data connectivity) retrieves live transaction data after an applicant links their bank account, so there is no document involved. Bank statement analysis software works on the statements applicants submit as files. Most lenders need both, because a meaningful share of applicants decline or fail to link accounts and upload statements instead.
Only if it includes a fraud layer. Conversion on its own treats every submitted document as genuine and will turn a forged statement into clean data. Most conversion-first vendors now offer fraud checks as a companion feature, so the question to ask is what that layer inspects. Fraud-aware platforms examine metadata, fonts, pixel-level artifacts, template reuse across a document network, and internal consistency to flag fraudulent transactions and fake bank statements before their data is used, including fully AI-generated statements that look flawless to a reviewer.
Three months of statements smooths out one-time deposits and reveals recurring income, spending patterns, and balance trends. It is also no longer a fraud deterrent by itself: template sites and AI tools produce internally consistent 3 months of fake bank statements as easily as one, which is why the multi-statement convention needs verification behind it.
Yes; that is the baseline. Look for coverage of digital PDF bank statements, scanned documents, and photos of printed statements, of any page count, including statements spanning multiple bank accounts and files that combine multiple accounts at one institution. Coverage should extend to statements from small regional banks and credit unions, not just major institutions, since those formats are where extraction accuracy usually degrades.
Accuracy varies widely by vendor and by input quality, which is why field-level testing on your own documents matters more than quoted benchmarks. AI-powered software pairs OCR with LLM-based parsing to interpret tables, layouts, and cross-page relationships, which holds up better on complex statements than OCR alone.
Consumer and business lenders, banks, credit unions, equipment financing companies, fintechs, lending platforms, and property managers. Common teams include underwriters, credit operations, fraud analysts, and risk leaders, in any workflow where financial insights must come from submitted documents.
Look for API-first platforms with REST endpoints for submission and results, webhook support for real-time events, and structured outputs that fit your existing systems, whether that is an LOS or a decision engine, so results speed up decision making instead of creating a new queue. Integration documentation should be public and current; Inscribe's is at docs.inscribe.ai.
Pricing is typically per document, per page, or per application, often with volume tiers. Total cost depends on your monthly document volume, how multi-page statements are counted, and whether fraud detection is bundled or priced separately. Model your real volumes during the pilot rather than comparing list prices.
About the author
Mika Pham is a Marketing Specialist at Inscribe, where she focuses on SEO execution and event marketing. She comes from Veryfi, a fintech B2B SaaS company in the document processing and fraud detection space, giving her direct industry context for the problems Inscribe's customers face. She holds an Engineering degree from Vanderbilt University.
Learn More
Dive deeper into credit analysis

What will our AI Agents find in your documents?
Start your free trial to catch more fraud, faster.


